What is the scope and industry significance of the Services Procurement Market?
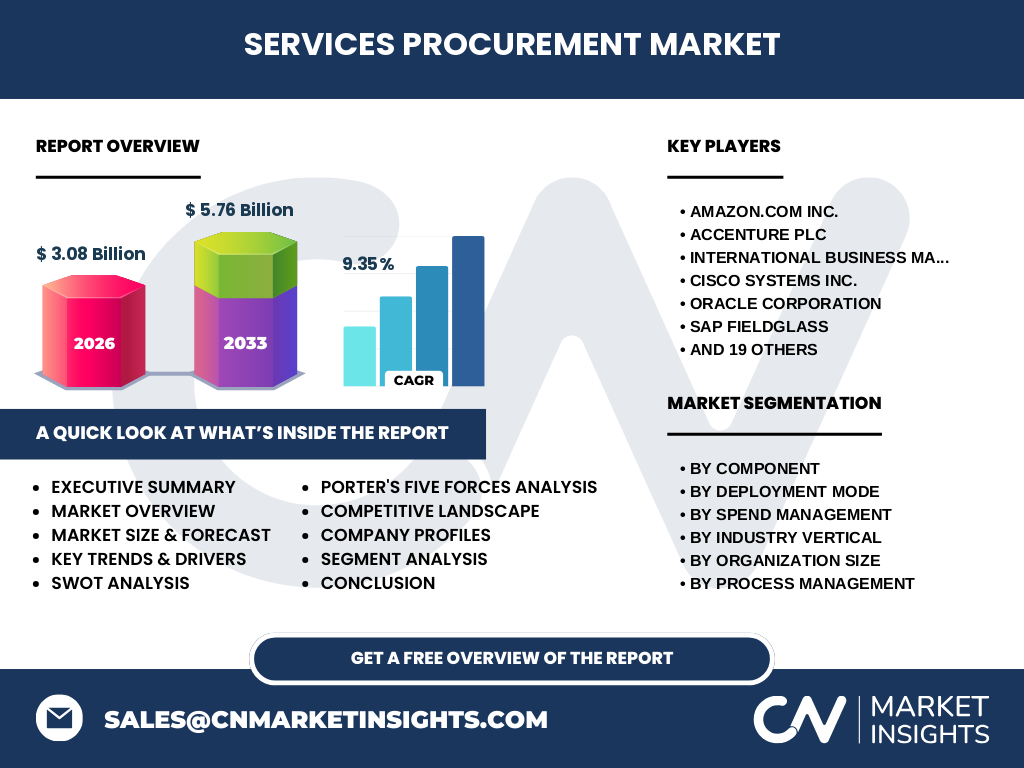
Our analysis indicates that the Services Procurement Market reached 3.08 Billion in 2026, serving as the definitive operational backbone for managing complex external workforces, contingent labor, and statement-of-work (SOW) services. Enterprises increasingly rely on these specialized procurement architectures to enforce compliance with labor regulations, such as the EU Working Time Directive and local wage laws, while optimizing non-employee spend across global operations.
Key market drivers, restraints, challenges, and opportunities shaping Services Procurement Market
The market is propelled by a 9.35% CAGR from 2027 to 2033, driven by the acute need for enterprise cost optimization amid macroeconomic volatility. However, adoption faces severe restraints regarding legacy enterprise resource planning (ERP) integration friction and strict data residency mandates enforced by regulatory bodies like the European Banking Authority. Opportunities flourish in integrating advanced machine learning for predictive contingent labor budgeting.
Emerging trends and growth patterns in Services Procurement Market
The shift toward total workforce management platforms represents a pivotal industry inflection point. Organizations are abandoning siloed vendor management systems in favor of unified ecosystems that handle both contingent labor and specialized professional services. This trend favors agile software innovators capable of delivering real-time spend visibility and automated supplier risk management without disrupting legacy procurement workflows.
COVID-19 impact analysis — how the pandemic affected Services Procurement Market and the recovery trajectory
The pandemic exposed extreme vulnerabilities in traditional enterprise supply chains, forcing a structural migration toward cloud-based procurement agility. As remote workforces expanded globally, demand surged for digital-first contract execution and automated supplier onboarding solutions. The recovery trajectory established a permanent baseline where real-time spend analytics and agile transaction management are mandatory risk mitigation tools rather than optional enhancements.
Competitive landscape in the Services Procurement Market
The competitive landscape features intense rivalry among software giants and pure-play vendors, including SAP Fieldglass, Coupa Software Incorporated, and Beeline B.V. Market concentration is moderate to high, with enterprise buyers demanding end-to-end functionality encompassing everything from supplier discovery to invoice management. Strategic differentiation increasingly hinges on proprietary analytics engines and seamless integration with major human capital management frameworks.
Executive summary of key findings
Our research confirms a dramatic expansion phase, projecting the market to surge from 3.08 Billion in 2026 to 5.76 Billion by 2033. Strategic procurement leaders are prioritizing cloud deployments and automated workflow management to eliminate leakage in non-employee spend. Organizations failing to adopt advanced category and contract management solutions risk severe cost inefficiencies and regulatory penalties in managing global external talent.
Market forecast from 2027 to 2033
The data projects the market to expand robustly at a 9.35% CAGR, escalating from 3.08 Billion in 2026 to a valuation of 5.76 Billion by 2033. This accelerated trajectory reflects heightened enterprise urgency around digital transformation in procurement operations, particularly within capital-intensive sectors seeking granular cost optimization and risk mitigation across multi-tier supplier networks.
Segmentation analysis of the Services Procurement Market
Our segmentation framework breaks down the market by component, deployment mode, spend management, industry vertical, organization size, and specialized functional modules including Transaction Management, Strategic Sourcing, Process Management, Spend Management, Contract Management, and Category Management. Cloud deployments dominate over on-premises models due to superior scalability, while large enterprises and SMEs leverage distinct modules like spend analytics and supplier risk management to control external expenditures.
Regional market analysis and geographic distribution
Geographic performance exhibits distinct regulatory and economic maturity patterns across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America commands the largest market share, accelerated by early enterprise adoption of contingent workforce platforms. Meanwhile, Europe demonstrates stringent compliance-driven growth, heavily shaped by GDPR and national labor laws governing independent contractors and service providers.
In-depth regional review of procurement dynamics
A closer examination reveals that North American adoption is heavily concentrated around IT and financial services hubs requiring sophisticated supplier discovery and contract compliance tools. In contrast, the Asia-Pacific region represents the fastest-growing frontier, propelled by rapid manufacturing digitization in logistics hubs across Southeast Asia and robust software development outsourcing in South Asia, necessitating advanced invoice management and workflow automation.
Company profiles and strategic positioning
Industry leaders such as Amazon.com Inc., Accenture plc, Oracle Corporation, and Tata Consultancy Services Limited utilize distinct positioning strategies ranging from broad enterprise cloud suites to specialized consulting-led procurement execution. Companies like GEP Solutions Pvt. Ltd. and Zycus Inc. leverage proprietary artificial intelligence engines to capture market share in automated spend visibility and strategic sourcing optimization.
Porter's Five Forces analysis of the Services Procurement Market
Bargaining power of buyers remains high due to intense vendor competition and abundant software alternatives. Threat of new entrants is moderate, constrained by high switching costs and complex security compliance requirements mandated by enterprise buyers. Rivalry among established platform providers like Coupa Software Incorporated and SAP Fieldglass drives continuous innovation in predictive analytics and user experience.
SWOT analysis of the industry ecosystem
Key strengths include robust technological innovation in cloud architecture and deep workflow automation. Weaknesses involve high initial deployment friction and integration costs with legacy ERP systems. Opportunities lie in expanding SME market penetration and embedding generative artificial intelligence for contract negotiation, while threats stem from evolving global data privacy regulations and macroeconomic uncertainty impacting corporate budgets.
Value chain analysis and industry structure
The value chain spans from foundational software development and raw data ingestion to advanced spend analytics, strategic sourcing execution, and end-user transaction management. Technology innovators and platform providers sit at the core, transforming raw supplier data into actionable intelligence for enterprise procurement teams, ultimately streamlining order fulfillment and supplier invoice processing for global corporations.
Investment insights and strategic recommendations
High-potential areas for venture capital and corporate investment center on cloud-native solutions offering automated supplier risk management and real-time spend visibility. Investors should prioritize platform providers demonstrating strong integration capabilities with major financial and human capital systems, as enterprise buyers increasingly reject siloed point solutions in favor of unified, end-to-end procurement ecosystems.
Conclusion and key takeaways for stakeholders
The Services Procurement Market is at a critical juncture, scaling rapidly toward 5.76 Billion by 2033 driven by a 9.35% CAGR. Stakeholders must embrace cloud deployment, comprehensive contract management, and intelligent spend analytics to maintain a competitive advantage in an increasingly regulated and globalized operational environment.
Research methodology for baseline estimates
Our research methodology employs a rigorous triangulation approach combining primary stakeholder interviews with chief procurement officers, exhaustive trade registry data from international labor organizations, and secondary macroeconomic indicators. Baseline estimates are cross-referenced with financial reports from market participants like Infosys Limited, Wipro Limited, and Capgemini SE to ensure absolute data integrity and market accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics, segmentation breakdowns, and competitive positioning within the Services Procurement Market from 2027 to 2033, utilizing 2026 as the base financial year set at 3.08 Billion. Limitations include excluding informal, undocumented black-market labor transactions and focusing strictly on enterprise-grade software deployments, managed service programs, and structured business-to-business procurement agreements.
Recent developments in the ecosystem
Recent strategic moves feature aggressive product launches focusing on generative artificial intelligence integration for contract creation and negotiation by market leaders like JAGGAER Inc. and WorkMarket Inc. Strategic partnerships between cloud platform providers and major global system integrators are accelerating, aimed at streamlining complex multinational rollouts and enhancing compliance monitoring across volatile cross-border supply chains.